September 2026 excavator exports: Europe down 23%, Latin America up 96%
China exported US.95 billion of construction machinery in September 2026, up 31.9% year on year — but the growth came almost entirely from outside Europe. By value, exports to Latin America rose 96% and to North America 98%, while exports to Europe fell 23%. For anyone buying excavator parts, that split is more useful than the headline number.
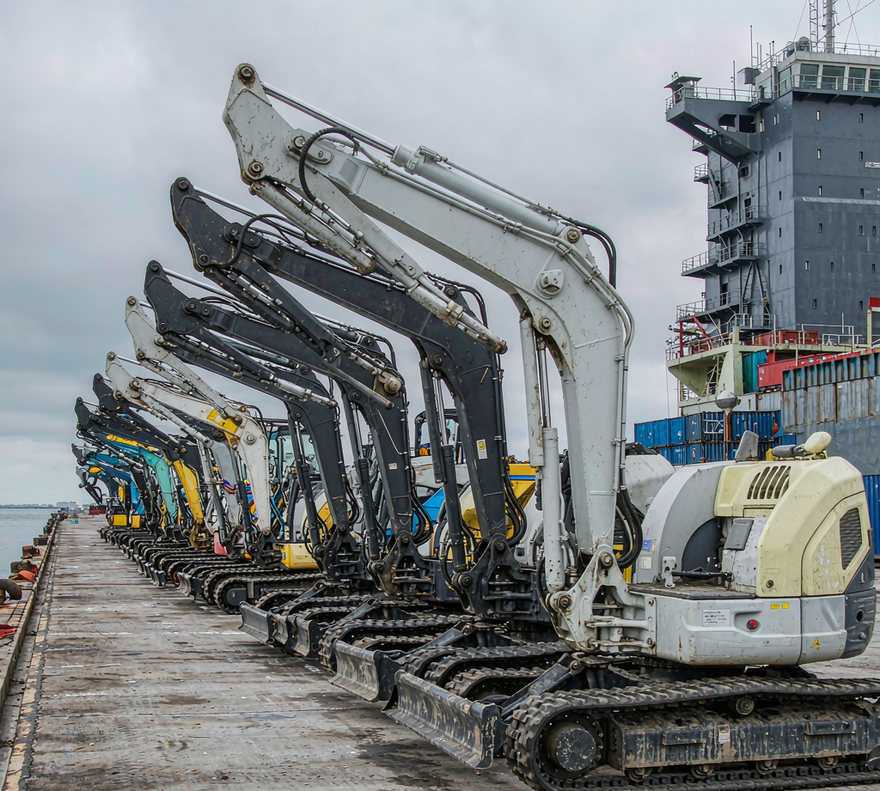
What did the September 2026 customs data actually show?
The figures come from China customs data compiled in a brokerage note published on 23 October 2026. Construction machinery exports for the month were US.952 billion, up 31.9%. Excavator export value was RMB 7.67 billion, up 15.4% — growing, but at roughly half the pace of the sector as a whole, which tells you the mix is shifting toward other machine types.
By destination region, the value growth rates were:
- Latin America: +96%
- North America: +98%
- Oceania: +72%
- Asia: +24%
- Africa: +3%
- Europe: −23%
Unit flows for excavators in the same month put the United States at 7,494 machines, Indonesia at 2,324, France at 1,496, Australia at 907, Brazil at 850 and Nigeria at 268.
Why does a 23% fall into Europe matter if France still took 1,496 machines?
Because it is a value story, not a volume collapse. France remained one of the largest single destinations in the month. A 23% drop in value alongside a still-large unit count points to a cheaper mix — smaller machines, or more competition on price — rather than European buyers walking away.
The honest position is that a single month of customs data does not explain itself. The September figure lands in the same period as EU and UK trade measures on Chinese-built excavators and tightening Stage V emissions requirements, both of which affect which machines can be sold where and at what cost. Those are context, not proven cause, and one month is not a trend.
What does the split mean for parts demand?
Latin America and North America: new machines, then warranty and first-fill parts
A machine delivered in late 2026 spends its first two to three years on dealer service and OEM parts. Undercarriage and bucket wear parts — the items that actually consume a maintenance budget — start moving in volume somewhere around 2,000 to 4,000 hours. The parts demand created by this quarter's shipments arrives in 2027 and 2028, not now. That is the window in which an aftermarket supplier either has the part numbers ready or does not.
Europe: older fleet, rebuild rather than replace
When new machine deliveries slow, the average age of the working fleet rises, and a rising fleet age is good for rebuild parts: track chains, rollers, idlers, track shoes, pins and bushings. A contractor facing a longer replacement cycle spends on the undercarriage instead. The mix shifts from whole assemblies toward components.
Africa: the number is doing less than it looks
Africa at +3% by value against 268 excavator units to Nigeria is worth reading carefully. Nigeria is one of the largest single African destinations for Chinese machines, so 268 units is a modest month, and a near-flat regional value figure says the growth is coming from other machine types or other countries rather than from excavators. Plan African stock on your own order history, not on the regional aggregate.
Asia and Africa: steady, price-sensitive
Asia at +24% and Africa at +3% are the least dramatic numbers in the table and the most predictable demand. These are markets where a bucket pin is bought on price and fit, and where a supplier's real advantage is having the right part number in stock rather than a marketing story.
What should a buyer do with this?
Two practical things. First, if you are stocking for Latin America or North America, place wear-part orders earlier than the machine delivery suggests — factory capacity in Shandong is shared, and the fourth quarter is the tightest booking period of the year before Chinese New Year. Second, do not read a single month as a market signal. Watch the regional value split across three or four consecutive months before changing a stocking plan.
For context on where JALE sits: we are a parts manufacturer in Shandong, not a machine exporter, and we do not appear in any of the figures above. What the data tells us is where machines are going, which is where their excavator parts will eventually be needed. That is the only claim we are making.
,000 went viral in Norway this autumn, and behind that video sits hard data: construction machinery exports reached US.373 billion in the first half of 2026, up 21.7 percent year on year according to the China Construction Machinery Association, with compact equipment and micro excavators driving the fastest growth.
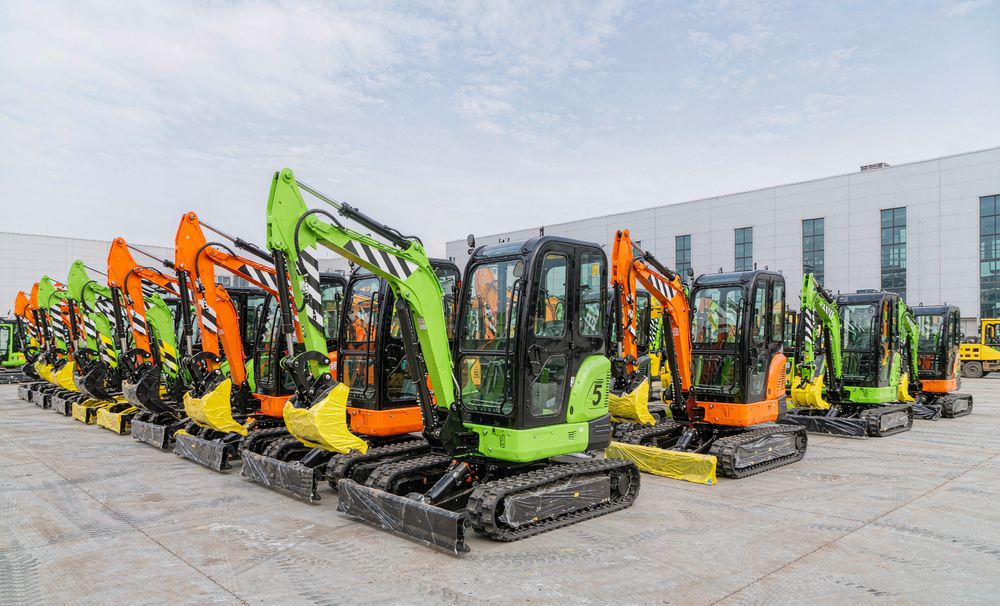
What do the H1 2026 export numbers show?
The headline figures reported by Chinese state media in late October, drawn from industry association statistics: excavator exports exceeded domestic sales for the eighth consecutive month, and cumulative excavator exports passed 85,000 units in the first seven months of 2026, up more than 31 percent year on year. Exports to the European Union reached US.626 billion, up 28.9 percent. Industry forecasts put China's compact construction machinery sales for 2026 above 180,000 units, with micro excavators making up more than 60 percent of that, roughly 110,000 machines. Trade commentary attributes the shift to buyers outside the traditional channel: private owners, small farms and tradespeople in Europe and South America discovering these machines through social media and cross-border e-commerce rather than dealer networks.
Why does this matter to parts buyers?
Because every one of those machines is a compact wear-parts consumer. A 1 to 3 tonne excavator still runs bucket pins and bushings, teeth, track rollers and sprockets; it just runs them at smaller envelopes and tighter tolerances than a 20 tonne machine. The parts market for this segment behaves differently from the large-machine market in three ways:
- Volumes are high and per-unit margins are thin, so parts supply consolidates around the same Shandong manufacturing clusters that build the machines.
- Many compact machines are sold direct to first-time owners, so sourcing spare parts is often the owner's first experience with the brand. A parts page that does not answer "which pin fits my machine" loses that buyer instantly.
- Fleet-scale after-sales networks, the normal channel for 20 tonne iron, barely exist for micro machines, which pushes owners toward online parts suppliers and pushes suppliers toward clear part-number discipline.
What does this mean for a Shandong parts maker?
JALE Excavator Parts is a Shandong manufacturer of excavator wear parts, and it sits inside the same industrial cluster that is shipping these machines. Unlike most parts suppliers, it also builds its own compact range, including the JALE08, JALE10-1 and JALE12 mini excavators, so the fit between a small machine and its pins, bushings and undercarriage parts is designed rather than reverse-engineered.
Do compact machines need different parts discipline?
The wear parts are the same families, but the failure pattern is not. A micro excavator's pins and bushings are physically smaller, so a few tenths of a millimetre of wear is a larger share of the original clearance, and the symptoms, play at the bucket ear, grease that will not hold, a knocking sound on direction change, arrive sooner relative to machine hours. Owners who would never inspect a 20 tonne machine weekly can and should walk around a 1 tonne machine weekly: two grease strokes per pin, a visual check that the bucket ears have not bell-mouthed, and a feel for slop at the linkage. The parts themselves are cheap; the deciding factor is knowing the pin diameter and ear spacing before ordering, because a 25 mm and a 30 mm pin look identical in a photo.
One honest caveat: no association figures have been published for compact-segment parts demand specifically, so any claim about its size would be guesswork. What the export data does establish is the installed base: over 100,000 micro and compact machines a year are entering service, largely with owners who have no dealer relationship. Their pins, bushings and teeth will be replaced on wear, on the owner's budget, from whichever supplier answers first with the right dimensions. That is the market segment forming behind the headline number, and it buys the same discipline this site has always sold: correct part numbers, honest steel grades, and hardware that fits the first time.
,000 went viral in Norway this autumn, and behind that video sits hard data: construction machinery exports reached US.373 billion in the first half of 2026, up 21.7 percent year on year according to the China Construction Machinery Association, with compact equipment and micro excavators driving the fastest growth.
What do the H1 2026 export numbers show?
The headline figures reported by Chinese state media in late October, drawn from industry association statistics: excavator exports exceeded domestic sales for the eighth consecutive month, and cumulative excavator exports passed 85,000 units in the first seven months of 2026, up more than 31 percent year on year. Exports to the European Union reached US.626 billion, up 28.9 percent. Industry forecasts put China's compact construction machinery sales for 2026 above 180,000 units, with micro excavators making up more than 60 percent of that, roughly 110,000 machines. Trade commentary attributes the shift to buyers outside the traditional channel: private owners, small farms and tradespeople in Europe and South America discovering these machines through social media and cross-border e-commerce rather than dealer networks.
Why does this matter to parts buyers?
Because every one of those machines is a compact wear-parts consumer. A 1 to 3 tonne excavator still runs bucket pins and bushings, teeth, track rollers and sprockets; it just runs them at smaller envelopes and tighter tolerances than a 20 tonne machine. The parts market for this segment behaves differently from the large-machine market in three ways:
- Volumes are high and per-unit margins are thin, so parts supply consolidates around the same Shandong manufacturing clusters that build the machines.
- Many compact machines are sold direct to first-time owners, so sourcing spare parts is often the owner's first experience with the brand. A parts page that does not answer "which pin fits my machine" loses that buyer instantly.
- Fleet-scale after-sales networks, the normal channel for 20 tonne iron, barely exist for micro machines, which pushes owners toward online parts suppliers and pushes suppliers toward clear part-number discipline.
What does this mean for a Shandong parts maker?
JALE Excavator Parts is a Shandong manufacturer of excavator wear parts, and it sits inside the same industrial cluster that is shipping these machines. Unlike most parts suppliers, it also builds its own compact range, including the JALE08 and JALE12 mini excavators, so the fit between a small machine and its pins, bushings and undercarriage parts is designed rather than reverse-engineered.
Do compact machines need different parts discipline?
The wear parts are the same families, but the failure pattern is not. A micro excavator's pins and bushings are physically smaller, so a few tenths of a millimetre of wear is a larger share of the original clearance, and the symptoms, play at the bucket ear, grease that will not hold, a knocking sound on direction change, arrive sooner relative to machine hours. Owners who would never inspect a 20 tonne machine weekly can and should walk around a 1 tonne machine weekly: two grease strokes per pin, a visual check that the bucket ears have not bell-mouthed, and a feel for slop at the linkage. The parts themselves are cheap; the deciding factor is knowing the pin diameter and ear spacing before ordering, because a 25 mm and a 30 mm pin look identical in a photo.
One honest caveat: no association figures have been published for compact-segment parts demand specifically, so any claim about its size would be guesswork. What the export data does establish is the installed base: over 100,000 micro and compact machines a year are entering service, largely with owners who have no dealer relationship. Their pins, bushings and teeth will be replaced on wear, on the owner's budget, from whichever supplier answers first with the right dimensions. That is the market segment forming behind the headline number, and it buys the same discipline this site has always sold: correct part numbers, honest steel grades, and hardware that fits the first time.
.31 billion, up 47%, and to Latin America at US.03 billion, up 60.7%. Longer routes make schedule reliability worth more than a few days of inland saving, which is why the port and the carrier matter more than the canal itself.
What it means for a parts order in practice
Production time does not move. Machining, heat treatment and packing run at the same pace whichever port the container leaves from. What a shorter inland leg changes is the buffer a supplier needs between finishing an order and handing it to the carrier, and at the margin how much working capital sits in a container on a truck.
For the buyer, the response is unchanged: plan stock against ocean transit plus clearance, not against the inland leg, and ask for the port and the sailing date rather than a single lead-time number. The parts themselves — bucket pins and bushings, track chains, bucket teeth — are priced by steel grade and machining hours, not by which river they floated down.
.90 billion, up 13.9%; to Europe, US.59 billion, up 4.2%. The growth is elsewhere: Africa at US.31 billion, up 47%, and Latin America at US.03 billion, up 60.7%.
That regional split matters for spare-parts planning. Mature markets in Europe are growing slowly, while the fastest-growing destinations are markets where machines work long hours in abrasive conditions and where the dealer and service network is thinner — exactly the profile that generates high wear-parts consumption. Trade-press analysis attributes a large share of African excavator demand to mining, and mining duty is brutal on undercarriage and on ground-engaging tools.
What should buyers and distributors plan for?
Stock the models that are actually in the field, not the models in the press release. On the evidence of the last few years that means the mainstream 20–30 tonne classes and the household names built around them — PC200 and PC300 class machines, the 320 and 330 class, the EX200 class, the R210 class and the DX225 class — plus the undercarriage groups that fit them. Those are the machines absorbing pins, bushings and track components in volume.
Do not build stock around electric-specific parts yet. At 0.6% penetration there is no volume aftermarket, and the common parts on those machines are the same parts you already carry.
Finally, plan for the replacement cycle, not just the new-machine market. Chinese trade-press analysis puts the domestic replacement cycle at roughly eight years, and with domestic sales now rising on the back of equipment replacement and emission-standard upgrades, a large second and third-owner population of machines is coming into its maintenance-heavy phase. That is the cohort that buys the most wear parts per machine — and it is a diesel cohort.
